

Top Austin, TX Software Companies With Best Stability & Growth (1,023)
Corporate Tools is proudly, stubbornly independent. No outside investors calling the shots. It’s just us choosing customers over profits, every time. We build the behind-the-scenes tools that keep businesses running: software, LLC filings, registered agent service, website and domain registration, address services… basically all the unglamorous stuff that makes companies actually work. We’ve grown into one of the largest B2B providers in...

Corporate Tools LLC's Top Stability & Growth Strengths
Diversified Revenue Streams: The company highlights expansion beyond core registered‑agent/entity services into telecommunications, domain registration, credit card processing, and data centers. This breadth indicates multiple monetization channels rather than reliance on a single line of business.
Product Line Growth: Corporate Tools describes broadening its offering to include entity management software, nationwide filings/logistics, compliance tooling, and related infrastructure. This expansion in scope aligns with continued scaling across a larger operating footprint.
Investor Backing & Capital Strength: Corporate Tools characterizes itself as independently owned and debt‑free. That footing suggests financial flexibility without dependence on external capital markets.
Atlassian creates teamwork solutions for high-performing teams. Our portfolio of collaboration and work management software products includes Jira, Confluence, Trello, Loom and Rovo. More than 300,000 businesses worldwide rely on Atlassian’s technology, including 80 percent of Fortune 500 companies. Our solutions support various business teams and they help organizations plan, track, and deliver their biggest ideas together.
Atlassian's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is expanding at strong double‑digit rates across recent quarters and the latest fiscal year, with cloud revenue and ARR also rising. Investor materials and quarterly updates highlight consistent momentum rather than a one‑off spike.
Strong Market Position & Advantage: Independent analyst recognitions position the company as a Leader across multiple core categories, and it serves a very large, global customer base including much of the Fortune 500. This broad market presence supports pricing power, cross‑sell, and durable demand.
Innovation-Driven Growth: Cloud migrations and newly introduced AI capabilities are cited as meaningful tailwinds for adoption and expansion. Product enhancements and platform integrations are associated with larger enterprise deals and a growing backlog of committed revenue.
Commerce (Nasdaq: CMRC) empowers businesses to innovate, grow, and thrive through an open, AI-driven commerce ecosystem. As the parent company of BigCommerce, Feedonomics, and Makeswift, we help brands unlock the full potential of their data, connect systems, and deliver seamless, personalized experiences across every channel. Visit commerce.com or follow us for more. #PoweredByCommerce

Commerce's Top Stability & Growth Strengths
Profitability: GAAP net income turned positive in Q1 and Q2 2026 and non‑GAAP operating margin improved year over year, indicating meaningful bottom‑line progress. Adjusted EBITDA also increased, supporting a trend toward sustainable earnings.
Cost & Operational Efficiency: A September 2026 operating plan targets approximately $60M–$80M in annualized cost savings and raised operating income guidance, reflecting disciplined execution. Positive operating cash flow and sequential margin gains point to improving operational leverage.
Future-Ready Strategy: Product moves highlight AI- and agentic‑commerce capabilities and payments initiatives (e.g., BigCommerce Payments by PayPal) across BigCommerce, Feedonomics, and Makeswift. This orientation suggests readiness to better monetize growing GMV and new channels.
.jpg)
At Braze, we believe in the passion of our people. We seek to ignite that passion by setting high standards, championing teamwork, and creating work-life harmony. We thrive when people add their unique perspectives to our ever-growing teams—and we strive to empower you to make an impact that fuels both you, and our business.
Braze's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased solidly year over year in both the latest quarter and the full fiscal year, with momentum characterized as robust and consistent across recent periods. Company materials indicate the expansion is driven by contributions from both existing and newly added customers.
Healthy Cash Flow: Free cash flow turned positive and rose meaningfully, alongside improvements in non-GAAP operating income. These trends indicate improving cash profitability even as GAAP profitability has yet to be reached.
Customer Loyalty & Retention: Net retention indicates expansion within existing accounts, and the cohort of larger enterprise customers has grown. Together, these signals point to durable upsell and cross-sell within the installed base.

AlertMedia helps organizations protect their people and businesses through all phases of an emergency. Our award-winning threat intelligence, emergency communication, and travel risk management solutions help companies of all sizes identify, respond to, and recover from critical events faster and more confidently. Our team of in-house intelligence analysts and meteorologists work around the clock to monitor thousands of data sources...

AlertMedia's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as having exceeded 40% year over year in 2022 and 273% growth over the Deloitte Fast 500 measurement period. Recent disclosures cite well over $100M in ARR and reporting of more than $100M in annual revenue.
Market Expansion: Customer footprint is reported at 3,500+ organizations across 150+ countries, with earlier periods adding 600+ customers and a London office opened to support rapid international growth. Partnerships and channel integrations are noted as expanding reach to multinational programs.
Product Line Growth: The platform has broadened through AI-powered launches (assistants, analytics, plan builders) and the acquisition of Pyrra to add social/digital threat intelligence. Continued investment in 2026, including new leadership roles focused on AI, underscores ongoing product expansion.
 copy.jpg)
At 8am, our vision is to power a world where professionals thrive. We start every day on a mission to empower professionals with the most trusted, innovative technology to deliver world-class outcomes for their clients and exceptional financial results for their business. They count on our purpose-built solutions to simplify operations, ensure compliance, and fuel profitable growth, so they can...
8am (Formerly AffiniPay)'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is portrayed as rising consistently, with multi-year acceleration alongside increases in recurring revenue and total payments processed. Company communications across 2024–2026 emphasize continued momentum rather than stagnation.
Product Line Growth: The portfolio expanded beyond payments into practice management, financial tools, and AI capabilities, unifying brands such as LawPay, MyCase, CasePeer, DocketWise, and CPACharge. This broader offering is presented as fueling adoption and deeper engagement among professionals.
Investor Backing & Capital Strength: Major private-equity investors partnered with the company in 2024 to support its next phase of expansion. This backing is framed as enabling acquisitions, platform development, and scaling initiatives.
For more than two decades, Imprivata has been redefining how life- and mission-critical industries secure and manage digital identities. We empower healthcare and enterprise organizations to enable fast, compliant, and secure access to technology—allowing clinicians and staff to stay focused on what matters most: patient care and operational excellence. Our digital identity platform is purpose-built for complex environments where every second...

Imprivata's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as sizable and growing rapidly, with independent reporting and credit analyses pointing to continued double‑digit expansion. ARR and ACV are characterized as increasing consistently since 2022.
Customer Loyalty & Retention: Retention is depicted as very high, with consistent expansion within existing accounts that supports sustained recurring revenue growth. Commentary highlights strong share‑of‑wallet gains and durable renewals across healthcare customers.
Product Line Growth: The portfolio has broadened through repeated acquisitions (e.g., SecureLink, Verosint) and new capabilities such as passwordless authentication and agentic identity management. These moves signal active investment to expand addressable use cases and deepen the platform.

Managing a technology estate has never been a bigger challenge. Hardware, software, and users can be anywhere at any time, making IT environments extremely dynamic and often complex. A seemingly simple question has become terribly difficult to answer: ‘Who is using what device?’ CIO's, CTO's, IT managers, ... have to make decisions that are often based on scattered, out of date,...
Lansweeper's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor announcements indicate substantial support for the next phase of growth, including Bridgepoint’s 2026 agreement to acquire a majority stake with plans for product/AI investment, international expansion and selective M&A. Earlier growth capital from Insight Partners in 2021 further underscores access to funding for scaling.
Product Line Growth: Acquisitions such as Fing (2020), Cloudockit (2022) and Redjack (July 2025) expanded the platform into passive network discovery and application dependency mapping. Available materials describe a shift from traditional IT asset discovery toward a broader Technology/Cyber Asset Intelligence platform.
Strong Hiring & Retention: Workforce estimates show headcount rising from roughly 404 in 2024 to about 469 in 2025 and remaining around that level in 2026, suggesting continued organizational expansion. Company pages reference 400+ to ~450 colleagues, consistent with active hiring.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased year over year in the latest quarters, with momentum accelerating into Q2 2026. Monetization per user improved, helping top-line growth outpace audience expansion.
Healthy Cash Flow: Adjusted EBITDA and free cash flow rose sharply, and the company generated positive free cash flow in the latest quarter. These gains indicate stronger operating leverage versus a year earlier.
Diversified Revenue Streams: Subscription and other direct-revenue products such as Snapchat+ expanded rapidly alongside core advertising. “Other revenue” grew significantly and the direct-revenue run rate scaled materially.

Apptronik is building robots for the real world to improve human quality of life and to help solve the ever-increasing labor shortage problem. Our team has been building some of the most advanced robots on the planet for years, dating back to the DARPA Robotics Challenge. We apply our expertise across the full robotics stack to some of the most...
Apptronik's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor participation is substantial, with nearly $1B raised across Series A tranches and backing from corporates like Google and Mercedes‑Benz to fund production and deployment. Feedback suggests this capital base is intended to accelerate scaling of Apollo and broader operations.
Strategic Partnerships: Partnerships span Mercedes‑Benz, GXO Logistics, Jabil, and Google DeepMind, moving Apollo from demos into pilots and industrial integrations. These relationships indicate advancing commercialization and access to manufacturing and AI capabilities.
Strong Hiring & Retention: Headcount expanded into the hundreds with senior hires from Waymo, Boston Dynamics, and Amazon to drive commercialization. Public statements note continued hiring to support production, facilities build‑out, and deployments.

We offer a source to pay solution designed for the energy sector. It streamlines the entire process from finding suppliers to issuing payments. Our goal is to strengthen alignment between field workers and corporate offices.
RigUp's Top Stability & Growth Strengths
Strong Revenue Growth: Historical metrics indicate rapid scaling, with gross revenue rising from under $300M in 2018 to roughly $900M in 2020. Platform volume also surpassed $2B in 2019 alongside very strong year-over-year growth at that time.
Investor Backing & Capital Strength: The company secured major financings, including $300M rounds in 2019 and 2021 at valuations of about $1.9B and $2.9B, bringing total funding above $750M. These rounds signal strong investor confidence during periods when the business was scaling across customers and service categories.
Product Line Growth: Offerings expanded beyond a labor marketplace into an energy-specific source-to-pay and vendor management platform, with additions such as bid management, technology licensing, and an engineering acquisition. Recent moves like launching vendor management, licensing Shell’s U‑lateral technology, and acquiring Codeco‑Vanoco Engineering suggest ongoing product and capability expansion.

Iodine is an enterprise AI company that is championing a radical rethink of how to create value for healthcare professionals, leaders, and their organizations: automating complex clinical tasks, generating insights and empowering intelligent care. We profoundly believe the future of healthcare, and the survival of healthcare systems, rests in a strong, symbiotic relationship between dedicated clinicians and executives who do...
Iodine Software's Top Stability & Growth Strengths
Market Expansion: The client base appears to have grown from 800+ hospitals in 2021 to more than 1,000 by the October 2025 acquisition, indicating broader market reach. The buyer also stated the deal would expand its total addressable market by more than 15%.
Product Line Growth: Offerings broadened through acquisitions of Artifact Health and ChartWise and launches such as AwareUM and pre-bill capabilities. This reflects expansion from core CDI into utilization management and adjacent mid–revenue-cycle workflows.
Investor Backing & Capital Strength: The company reached a valuation of about $1 billion in 2021 and was acquired for approximately $1.25 billion in 2025. The acquirer characterized the business as a highly recurring subscription model expected to be accretive to its financial profile.
Cisco ThousandEyes is a Digital Experience Assurance platform that empowers organizations to deliver flawless digital experiences across every network – even the ones they don’t own. Powered by AI and an unmatched set of cloud, internet and enterprise network telemetry data, ThousandEyes enables IT teams to proactively detect, diagnose, and remediate issues – before they impact end- user experiences. ThousandEyes...
Cisco ThousandEyes's Top Stability & Growth Strengths
Strong Revenue Growth: Observability revenues are described as rising sharply across consecutive years, with ThousandEyes repeatedly identified as a primary contributor to that momentum. Growth continued thereafter even as the broader category’s pace moderated, indicating durable contribution from ThousandEyes.
Market Expansion: ThousandEyes has been embedded into Cisco’s Digital Experience Assurance and extended across enterprise networks, the public Internet, SaaS, and public-cloud environments. Customer penetration among large enterprises has increased materially since FY2020, signaling broader reach and adoption.
Product Line Growth: Cisco has continued to add capabilities such as Cloud Insights and Traffic Insights while integrating data from Meraki and Catalyst. These enhancements expand use cases beyond standalone monitoring toward end‑to‑end network assurance.
At Rapid7, our vision is to create a secure digital world for our customers, our industry, and our communities. We do this by harnessing our collective expertise and passion to challenge what’s possible and drive extraordinary impact. We’re building a dynamic and collaborative workplace where new ideas are welcome. Protecting 11,000+ customers against bad actors and threats means we’re continuing...
Rapid7's Top Stability & Growth Strengths
Profitability: Bottom-line performance is strengthening, with consistent earnings beats, improved non-GAAP operating income, and durable free cash flow. Management is prioritizing margin expansion alongside operational efficiency.
Healthy Cash Flow: The business is generating solid free cash flow, with recent periods and guidance pointing to sustained cash generation. This supports stability even as revenue growth moderates.
Strong Market Position & Advantage: The company is repeatedly recognized as a leader in MDR, exposure management, and SIEM by major analyst programs. A large global customer base underscores established scale in its core markets.
Enverus’ innovative technologies drive production and investment strategies, enable best practices for energy and commodity trading and risk management, and reduce costs through automated processes across critical business functions. Enverus is a strategic partner to more than 6,000 customers in 50 countries. Enverus is a portfolio company of Hellman & Friedman and Genstar Capital.
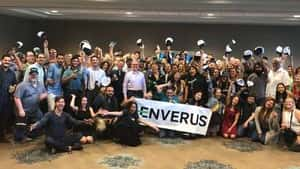
Enverus's Top Stability & Growth Strengths
Strong Revenue Growth: Feedback suggests recurring revenue expanded from crossing $500M ARR in 2023 to “approaching $600M” by May 2024. These company disclosures indicate meaningful momentum in subscription scale.
Product Line Growth: Feedback suggests the portfolio has broadened via acquisitions and new capabilities—including Pearl Street Technologies (grid interconnection), Spatial Business Systems (utility design automation), PDS Energy exchange platforms, and TGS’s A2D well‑log library. Enverus also cites rapid uptake of newer AI products and substantial growth in power and renewables since 2021.
Investor Backing & Capital Strength: Feedback suggests capital support is robust, with Blackstone agreeing in 2025 to acquire Enverus in a transaction reported around $6–6.5 billion. This major third‑party deal signals external validation of scale and resources for the next growth phase.

M-Files is redefining how work gets done. Our context-first document management system offers purpose-built business use cases—spanning universal and industry-specific workflows—to enable secure collaboration, automate processes, and ensure governance. Unlike traditional systems, M-Files organizes content around the context of your business, connecting documents to related people, projects, and transactions. With our unique metadata-driven architecture, organizations can model content in line...
M-Files's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is described as growing by more than 20% in 2023 and surpassing $100M, with 2025 concluding at record ARR and record ARR bookings. Nearly 500 new customers in 2025 reinforce continued topline momentum.
Diversified Customer Base: The company reports serving 6,000+ organizations across 100+ countries and added nearly 500 new customers in 2025. This breadth points to resilience across regions and segments.
Innovation-Driven Growth: Product velocity is highlighted with 240+ innovations delivered in 2025 and increased emphasis on AI and a context-first architecture. This cadence appears linked to ongoing enterprise adoption and expansion.

LogicMonitor® is the AI-first hybrid observability platform powering the next generation of digital infrastructure. LogicMonitor delivers complete visibility and actionable intelligence across on-premises, cloud, and edge environments. By anticipating issues before they strike, optimizing resources in real time, and enabling faster, smarter decisions, LogicMonitor helps IT and business leaders protect margins, accelerate innovation, and deliver exceptional digital experiences without compromise....
LogicMonitor's Top Stability & Growth Strengths
Strong Revenue Growth: ARR moved from surpassing $300M in June 2025 to exceeding $400M by May 2026, indicating a substantial year-over-year increase. The company also reported a 36% five-year organic CAGR in 2024, underscoring sustained momentum.
Product Line Growth: Edwin AI recurring revenue is reported to be growing around 200% year over year and contributing about one-third of total bookings. The December 2025 Catchpoint acquisition expanded capabilities into internet performance and digital experience monitoring.
Market Expansion: Larger enterprise accounts grew more than 25% year over year in 2025 and the company cited 700+ enterprise customers by late 2025. More than 30% of new customers came from outside the U.S., indicating ongoing international expansion.
.png)
Navan (Nasdaq: NAVN) is the leading all-in-one business travel, payments, and expense management platform that makes travel easy for frequent travelers. From finding flights and hotels to automating expense reconciliation, with 24/7 support along the way, Navan delivers an intuitive experience travelers love and finance teams rely on. See how Navan customers benefit and learn more at navan.com.
Navan's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is scaling at strong double-digit rates, reaching $702M in FY2026 and continuing to rise in subsequent quarters, with full‑year FY2027 guidance lifted into the low‑$900M range. Multiple updates indicate momentum in both reported results and outlook.
Healthy Cash Flow: Operating cash flow turned positive in FY2026 and free cash flow was also positive, alongside progress in non‑GAAP profitability in later quarters. These milestones suggest improving financial efficiency as scale increases.
Diversified Customer Base: The company reports 12,500+ active customers and continued wins with large enterprises across technology, manufacturing, and healthcare. This breadth points to demand resilience across multiple industries.
Upside is a technology company that increases the financial power of people and businesses in the real world. Our technology has helped millions of people get more purchasing power on the things they need, and tens of thousands of brick-and-mortar businesses earn measurable profit. Billions of dollars in commerce run through the Upside platform every year, and that value goes...
Upside's Top Stability & Growth Strengths
Market Expansion: Feedback suggests Upside expanded its marketplace with 14,669 new retailer locations and 1.6M new customers in 2025, alongside 128M transactions and a 64% YoY jump in restaurant transactions in July 2025. Feedback suggests category breadth deepened as well, with Taco Bell locations up 400% year over year and the network reaching 100,000+ retailers and ~35M consumers.
Strong Market Position & Advantage: Feedback suggests scale signals are substantial, including 35M consumers, 100,000+ retailers, >$1B cumulative cash back, and a rise in retailer incremental profit from $605M in 2024 to $707M in 2025. Feedback suggests repeated inclusion on growth rankings (e.g., Inc. 5000, Deloitte Technology Fast 500) further reflects momentum and visibility.
Strategic Partnerships: Feedback suggests partnerships and integrations broaden distribution and merchant adoption, including Marqeta and rollouts with large operators such as Save Mart and major QSR franchise groups. Feedback suggests these alliances extend Upside’s reach beyond the standalone app via partner networks that help drive consumer exposure and category expansion.
Grocery TV is the leading in-store retail media platform. Over 120 retailers partner with Grocery TV to modernize their stores and drive incremental revenue, while upholding a high-quality shopper experience. Grocery TV handles the complexities of operating an in-store media network so retailers can focus on what they do best—serving their customers. Reaching 1 in 4 Americans across nearly 6,000...
Grocery TV's Top Stability & Growth Strengths
Strong Revenue Growth: Multi‑year revenue gains are documented through repeated Inc. 5000 recognition and company‑reported growth over recent periods, indicating sustained top‑line momentum. Public materials consistently position revenue expansion alongside broader network scale increases.
Market Expansion: The network footprint has scaled quickly in stores, screens, and shopper reach, with continued additions of retailers and locations across the U.S. Announcements highlight step‑ups from earlier milestones to a materially larger national presence.
Strong Market Position & Advantage: The platform is frequently characterized as the largest in‑store retail media network for U.S. grocery, suggesting a scale advantage across banners and geographies. Third‑party trade coverage and company materials align on leadership by store and screen footprint.



