

Top Austin, TX Companies With Best Stability & Growth (3,878)
.jpg)
At Braze, we believe in the passion of our people. We seek to ignite that passion by setting high standards, championing teamwork, and creating work-life harmony. We thrive when people add their unique perspectives to our ever-growing teams—and we strive to empower you to make an impact that fuels both you, and our business.

Braze's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased solidly year over year in both the latest quarter and the full fiscal year, with momentum characterized as robust and consistent across recent periods. Company materials indicate the expansion is driven by contributions from both existing and newly added customers.
Healthy Cash Flow: Free cash flow turned positive and rose meaningfully, alongside improvements in non-GAAP operating income. These trends indicate improving cash profitability even as GAAP profitability has yet to be reached.
Customer Loyalty & Retention: Net retention indicates expansion within existing accounts, and the cohort of larger enterprise customers has grown. Together, these signals point to durable upsell and cross-sell within the installed base.
Build what’s next — with tech that matters PwC provides professional services across Audit and Assurance, Advisory and Tax — powered by a global network of over 370,000 people in 149 countries. You may know us for our business expertise, but technology is core to how we help clients move faster, build trust and deliver meaningful outcomes. As a technologist, you’ll work...

PwC's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Revenue has increased year over year to a new high, with all three major service lines posting gains despite a slower pace. Growth remains uneven by region, but the overall trajectory is upward over the last several fiscal years.
Future-Ready Strategy: Multi‑billion‑dollar investments in technology—especially nearly $1.5B in AI—along with acquisitions and scaling managed services indicate a deliberate pivot to future growth levers. Leadership attention to next‑generation audit and AI‑enabled capabilities underscores preparation for emerging demand.
Strong Market Position & Advantage: The organization is characterized as a leading global professional‑services network with broad scale across assurance, advisory, and tax and repeated external recognitions in select consulting categories. Reach across major multinational clients supports durable competitive positioning.

By automating and streamlining common accounting workflows to make them more efficient, FloQast is where accounting teams want to work so they can focus on what matters most, even when that’s just logging off on time. Whether automating reconciliations, documentation requests, or streamlining recurring accounting processes, such as the month-end close, financial reporting, or payroll, FloQast's platform enhances the way...
FloQast's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have surpassed $100M in 2023 and more than $200M by January 2026, roughly doubling in about two years. Recognition such as Deloitte Technology Fast 500 (with 289% reported multi-year revenue growth) and Inc. 5000 further underscores rapid expansion.
Market Expansion: International presence has broadened across the UK, EMEA (including DACH), and Australia/New Zealand, with continued EMEA growth noted. The customer base expanded to more than 3,500 global accounting teams by 2026, up from over 1,500 in 2021.
Investor Backing & Capital Strength: A $100M Series E in April 2024 at a reported $1.6B post-money valuation, corroborated by independent outlets, adds meaningful financial capacity. This funding is positioned to support scaling across product and international markets.
Atlassian creates teamwork solutions for high-performing teams. Our portfolio of collaboration and work management software products includes Jira, Confluence, Trello, Loom and Rovo. More than 300,000 businesses worldwide rely on Atlassian’s technology, including 80 percent of Fortune 500 companies. Our solutions support various business teams and they help organizations plan, track, and deliver their biggest ideas together.
Atlassian's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is expanding at strong double‑digit rates across recent quarters and the latest fiscal year, with cloud revenue and ARR also rising. Investor materials and quarterly updates highlight consistent momentum rather than a one‑off spike.
Strong Market Position & Advantage: Independent analyst recognitions position the company as a Leader across multiple core categories, and it serves a very large, global customer base including much of the Fortune 500. This broad market presence supports pricing power, cross‑sell, and durable demand.
Innovation-Driven Growth: Cloud migrations and newly introduced AI capabilities are cited as meaningful tailwinds for adoption and expansion. Product enhancements and platform integrations are associated with larger enterprise deals and a growing backlog of committed revenue.
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising year over year in 2025 and accelerating to double‑digit growth in early 2026, with management raising its full‑year outlook. Bookings and room nights are also increasing, reinforcing the top‑line trend.
Profitability: Profitability expanded faster than revenue in 2025 and continued to improve in 2026, including margin expansion in the latest quarter. This indicates operating leverage and stronger earnings quality alongside growth.
Diversified Revenue Streams: B2B has been growing much faster than the consumer business, and advertising/media also expanded strongly in 2025. Multiple engines—B2B, lodging, and advertising—are contributing materially to overall expansion.

Riot’s (NASDAQ: RIOT) vision is to be the world’s most trusted platform for powering and building digital infrastructure. Riot’s mission is to empower the future of digital infrastructure by positively impacting the sectors, networks, and communities that we touch. We believe that the combination of an innovative spirit and strong community partnership allows us to achieve best-in-class execution and create successful...

Riot Platforms, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is expanding sharply, with full-year 2025 rising to $647.4M from $376.7M and Q2 2026 up 14% year over year. Growth also appeared in Q1 2026, indicating momentum beyond a single quarter.
Diversified Revenue Streams: A new data-center segment has begun contributing ($33.2M in Q1 2026; $23.2M in Q2 2026) alongside mining and engineering, indicating revenue is no longer tied solely to self-mining. AI/HPC-related activity broadens the mix beyond Bitcoin exposure.
Strategic Partnerships: Agreements with AMD (initial 25 MW delivered and option exercised to 50 MW) and a 20-year, 191 MW lease with a frontier AI lab provide multi-year contracted demand. These relationships help monetize a reported ~2.0 GW fully approved power pipeline.
 copy.jpg)
At 8am, our vision is to power a world where professionals thrive. We start every day on a mission to empower professionals with the most trusted, innovative technology to deliver world-class outcomes for their clients and exceptional financial results for their business. They count on our purpose-built solutions to simplify operations, ensure compliance, and fuel profitable growth, so they can...

8am (Formerly AffiniPay)'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is portrayed as rising consistently, with multi-year acceleration alongside increases in recurring revenue and total payments processed. Company communications across 2024–2026 emphasize continued momentum rather than stagnation.
Product Line Growth: The portfolio expanded beyond payments into practice management, financial tools, and AI capabilities, unifying brands such as LawPay, MyCase, CasePeer, DocketWise, and CPACharge. This broader offering is presented as fueling adoption and deeper engagement among professionals.
Investor Backing & Capital Strength: Major private-equity investors partnered with the company in 2024 to support its next phase of expansion. This backing is framed as enabling acquisitions, platform development, and scaling initiatives.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased year over year in the latest quarters, with momentum accelerating into Q2 2026. Monetization per user improved, helping top-line growth outpace audience expansion.
Healthy Cash Flow: Adjusted EBITDA and free cash flow rose sharply, and the company generated positive free cash flow in the latest quarter. These gains indicate stronger operating leverage versus a year earlier.
Diversified Revenue Streams: Subscription and other direct-revenue products such as Snapchat+ expanded rapidly alongside core advertising. “Other revenue” grew significantly and the direct-revenue run rate scaled materially.
We started as a company that turned phones into walkie-talkies. Today, we modernize instant voice communication with our industry-leading push-to-talk technology to help mobile workers meet quickly changing, urgent, real-world challenges. We have the highest-rated walkie-talkie app, with over 8 billion messages sent per month and 170 million users in industries such as transportation, retail, construction, hospitality, healthcare, and more....
Zello's Top Stability & Growth Strengths
Strong Market Position & Advantage: Platform scale and enterprise deployments point to a defensible position, with 5 million monthly active users, 10 billion messages per month, and rollouts that reach tens of thousands of users across global organizations. Recognizable customers and broad industry presence in retail, aviation, transportation, construction, hospitality, and emergency services reinforce this standing.
Product Line Growth: Offerings have expanded beyond core push-to-talk to include Zello AI, Zello Kiosk, transcription, translation, analytics, and an SDK. This diversification suggests a widening set of enterprise use cases and deeper monetization pathways.
Profitability: The company characterizes itself as self-funded and profitable while continuing to list roles across AI/data, marketing, operations, and sales. This points to a business model capable of funding ongoing product and go‑to‑market investment.

EliseAI builds vertical AI agents for housing and healthcare — sectors that together make up nearly 40% of household spending. These agents automate high-volume workflows like leasing, maintenance, renewals, and patient intake, helping organizations cut costs, improve efficiency, and deliver better experiences. How does it work? EliseAI integrates directly into operational workflows: Housing: Manages leasing, maintenance, renewals, billing, and resident communication. Healthcare: Handles intake,...
EliseAI's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have surpassed $200M by June 2026 after crossing $100M in early 2025, with five consecutive years of 100% year-over-year growth. This consistent doubling signals rapid scaling at substantial revenue levels.
Investor Backing & Capital Strength: Funding rounds include $75M in 2024 at a valuation above $1B and a $250M Series E in 2025 at a reported $2.2B, with total capital raised cited at $400M+. Such late-stage financing and rising valuations indicate robust access to growth capital.
Strong Market Position & Advantage: Adoption is described as reaching roughly 1 in 6 U.S. apartments, with deep penetration among large property managers and hundreds of operators. Expansion into healthcare and notable distribution relationships have broadened its commercial footprint.
Ambiq® enables intelligence (AI and beyond) everywhere by delivering the lowest-power semiconductor solutions for battery-powered edge devices. As a pioneer in ultra-low power SoCs, Ambiq empowers wearables, IoT, smart home, healthcare, and industrial products with always-on, energy-efficient intelligence. Backed by our SPOT® technology and global innovation leadership, Ambiq is shaping the future of edge AI.
Ambiq 's Top Stability & Growth Strengths
Strong Revenue Growth: Recent quarters show rapid acceleration, with Q1 2026 net sales rising to $25.1M and Q2 reaching $33.9M alongside five consecutive quarters of sequential growth. Guidance for Q3 2026 of $36–37M indicates the trend may continue.
Cost & Operational Efficiency: Despite FY2025 revenue declining from 2024, gross profit increased to $32.1M and gross margin expanded materially. In Q2 2026, gross profit more than doubled year over year.
Investor Backing & Capital Strength: The company completed an IPO and upsized follow-on offerings in 2026, bolstering liquidity to over $360M in cash with no debt. It also added a dual listing in Singapore to broaden its investor base.
At Rapid7, our vision is to create a secure digital world for our customers, our industry, and our communities. We do this by harnessing our collective expertise and passion to challenge what’s possible and drive extraordinary impact. We’re building a dynamic and collaborative workplace where new ideas are welcome. Protecting 11,000+ customers against bad actors and threats means we’re continuing...
Rapid7's Top Stability & Growth Strengths
Profitability: Bottom-line performance is strengthening, with consistent earnings beats, improved non-GAAP operating income, and durable free cash flow. Management is prioritizing margin expansion alongside operational efficiency.
Healthy Cash Flow: The business is generating solid free cash flow, with recent periods and guidance pointing to sustained cash generation. This supports stability even as revenue growth moderates.
Strong Market Position & Advantage: The company is repeatedly recognized as a leader in MDR, exposure management, and SIEM by major analyst programs. A large global customer base underscores established scale in its core markets.

Managing a technology estate has never been a bigger challenge. Hardware, software, and users can be anywhere at any time, making IT environments extremely dynamic and often complex. A seemingly simple question has become terribly difficult to answer: ‘Who is using what device?’ CIO's, CTO's, IT managers, ... have to make decisions that are often based on scattered, out of date,...

Lansweeper's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor announcements indicate substantial support for the next phase of growth, including Bridgepoint’s 2026 agreement to acquire a majority stake with plans for product/AI investment, international expansion and selective M&A. Earlier growth capital from Insight Partners in 2021 further underscores access to funding for scaling.
Product Line Growth: Acquisitions such as Fing (2020), Cloudockit (2022) and Redjack (July 2025) expanded the platform into passive network discovery and application dependency mapping. Available materials describe a shift from traditional IT asset discovery toward a broader Technology/Cyber Asset Intelligence platform.
Strong Hiring & Retention: Workforce estimates show headcount rising from roughly 404 in 2024 to about 469 in 2025 and remaining around that level in 2026, suggesting continued organizational expansion. Company pages reference 400+ to ~450 colleagues, consistent with active hiring.

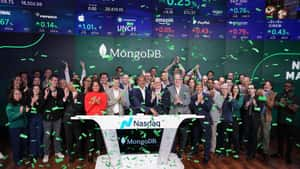
The database market is big. How big? Well, according to IDC, it’ll reach $153 billion by 2027. And MongoDB is at the forefront of that innovation with thousands of customers across the globe. We empower developers and businesses to build and deploy the applications they want, wherever they want.
MongoDB's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue expanded at a faster year-over-year pace in the latest quarter, with multi-year increases continuing from prior fiscal years and momentum building into fiscal 2027. Recent disclosures indicate broad-based gains across subscriptions and both cloud and self-managed offerings.
Healthy Cash Flow: Operating cash flow rose sharply year over year, and free cash flow expanded alongside improving operating margins. There is also a shift to GAAP profitability, signaling stronger operating leverage.
Customer Loyalty & Retention: A high net ARR expansion rate indicates existing customers are spending more over time, complementing steady additions to the total customer base. Atlas-related consumption from larger existing accounts is cited as a key driver of subscription growth.
ePayPolicy offers easier payment tools, built just for insurance. ePayPolicy's products bring insurance payments up to speed for agencies, carriers, MGAs and PFCs, with secure online payment pages, automated check processing, accounting reconciliation and more. 11,000+ insurance companies trust ePayPolicy and their expert support team to handle their payments every day.

ePayPolicy's Top Stability & Growth Strengths
Strong Revenue Growth: Inc. 5000 placements across five consecutive years, including a recent cycle with triple-digit multi‑year growth, indicate sustained revenue expansion. Earlier cycles cited even higher multi‑year growth, reinforcing a pattern of continued momentum.
Market Expansion: Customer count reportedly advanced from roughly 7,000 organizations to 10,000+ in 2025 and 12,000+ in 2026. This trajectory points to broader adoption across agencies, MGAs, carriers, and premium finance companies.
Investor Backing & Capital Strength: A new investment from LLR Partners in August 2025, alongside existing backer Serent Capital, was framed to support the next stage of growth. This institutional backing signals capacity to fund product innovation and go‑to‑market expansion.
Wise is a global technology company, building the best way to move and manage the world's money. With Wise Account and Wise Business, people and businesses can hold 40 currencies, move money between countries and spend money abroad. Large companies and banks use Wise technology too; an entirely new network for the world's money. Launched in 2011, Wise is one...

Wise's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue increased 19% in FY2026 to about $2.5bn and rose a further 25% year over year to $714m in Q1 FY2027, indicating continued top-line momentum. Growth is broad-based alongside rising customers and cross-border volumes.
Profitability: Income before tax reached roughly $660m in FY2026, equating to a 26% margin while volumes and usage scaled. Profitability held even as the company reduced take rates to remain competitive.
Diversified Revenue Streams: Card spend grew 37% to ~$44bn and customer holdings rose ~40% to ~$39bn in FY2026, with card and other revenue also expanding, indicating monetization beyond transfer fees. Wise Platform partnerships with banks further extend revenue sources beyond direct consumer transfers.
About Coursera: Coursera was launched in 2012 by Andrew Ng and Daphne Koller with a mission to provide universal access to world-class learning. Coursera partners with leading university and industry partners to offer a broad catalog of content and credentials, including courses, Specializations, Professional Certificates, and degrees. Coursera’s platform innovations — including AI-powered personalized guide and features, like Role Play and...
Coursera + Udemy 's Top Stability & Growth Strengths
Strong Market Position & Advantage: Scale of 290M+ learners and 12k–18k enterprise customers following the May 2026 combination signals a top-tier position in online learning. The combined platform also cites 95,000 creators and more than $1.5B of 2025 revenue, reinforcing competitive heft.
Strong Revenue Growth: Coursera delivered 9% revenue growth in 2025 and, after the Udemy combination, reported Q2 2026 revenue rose about 60% year over year. Management also raised full‑year 2026 reported revenue guidance to $1.220–$1.245 billion.
Diversified Revenue Streams: Multiple engines—consumer, enterprise, and subscriptions—are contributing, with Coursera’s consumer (+10%) and enterprise (+7%) segments growing in 2025. Udemy’s subscriptions (+8%) and Udemy Business revenue (+6%) expanded even as its consumer marketplace declined.

Founded in 2015, ReUp Education is the only organization that focuses exclusively on helping colleges and universities engage and re-enroll the more than 40 million US residents who have "stopped out" and support them until graduation, through our technology-enabled service. Today we build regional marketplaces to connect the supply of educational opportunities with the demand for skilled and credentialed workforce...

ReUp Education's Top Stability & Growth Strengths
Strong Revenue Growth: Inclusion on the Inc. 5000 list in both 2025 and 2026 is cited as direct evidence of multi‑year revenue growth. Consecutive recognition implies sustained top‑line expansion over the measured period.
Market Expansion: Partner counts rose from about 140+ colleges and universities across 33 states in 2025 to 160–180+ partners across 34 states by 2026. New statewide and institutional engagements in places such as Michigan, New Jersey, Massachusetts, and additional colleges indicate a widening geographic footprint.
Strategic Partnerships: State‑level programs (for example, New Jersey’s statewide re‑enrollment marketplace and Michigan’s multi‑institution initiative) show deepening relationships beyond single campuses. Ongoing additions like Montgomery County Community College and Mineral Area College reflect continued partner acquisition.
.png)
University Federal Credit Union (UFCU) was chartered in 1936, and it has grown into a strong, healthy, and growing financial cooperative, serving more than 250 universities, associations, and employers in Central Texas, Harris County, and Galveston County. We’re guided by the credit union motto of “Not for profit, not for charity, but for service,” and you’ll see it reflected every...
UFCU's Top Stability & Growth Strengths
Market Expansion: Recent openings across Georgetown, Cedar Park, Pflugerville, Austin Community College and Texas State University, plus entries into Houston, Manor, and Temple, indicate active geographic growth. Feedback suggests the footprint has expanded beyond Greater Austin into additional Texas markets.
Strong Market Position & Advantage: The organization is repeatedly described as the #1 credit union in the Austin MSA, leading in local deposits, members, and branches over multiple years. This sustained standing, alongside surpassing major membership milestones, signals durable competitive positioning in its core region.
Investor Backing & Capital Strength: Members’ equity increased meaningfully year over year and the net‑worth ratio reached a historical high near the 2025 period, with classifications indicating a well‑capitalized status. These indicators point to a solid capital base supporting continued scale and investment.
Grocery TV is the leading in-store retail media platform. Over 120 retailers partner with Grocery TV to modernize their stores and drive incremental revenue, while upholding a high-quality shopper experience. Grocery TV handles the complexities of operating an in-store media network so retailers can focus on what they do best—serving their customers. Reaching 1 in 4 Americans across nearly 6,000...
Grocery TV's Top Stability & Growth Strengths
Strong Revenue Growth: Multi‑year revenue gains are documented through repeated Inc. 5000 recognition and company‑reported growth over recent periods, indicating sustained top‑line momentum. Public materials consistently position revenue expansion alongside broader network scale increases.
Market Expansion: The network footprint has scaled quickly in stores, screens, and shopper reach, with continued additions of retailers and locations across the U.S. Announcements highlight step‑ups from earlier milestones to a materially larger national presence.
Strong Market Position & Advantage: The platform is frequently characterized as the largest in‑store retail media network for U.S. grocery, suggesting a scale advantage across banners and geographies. Third‑party trade coverage and company materials align on leadership by store and screen footprint.



