

Top Tech Companies in Austin, TX (3,833)
Upside is a technology company that increases the financial power of people and businesses in the real world. Our technology has helped millions of people get more purchasing power on the things they need, and tens of thousands of brick-and-mortar businesses earn measurable profit. Billions of dollars in commerce run through the Upside platform every year, and that value goes...
Upside's Top Stability & Growth Strengths
Market Expansion: Feedback suggests Upside expanded its marketplace with 14,669 new retailer locations and 1.6M new customers in 2025, alongside 128M transactions and a 64% YoY jump in restaurant transactions in July 2025. Feedback suggests category breadth deepened as well, with Taco Bell locations up 400% year over year and the network reaching 100,000+ retailers and ~35M consumers.
Strong Market Position & Advantage: Feedback suggests scale signals are substantial, including 35M consumers, 100,000+ retailers, >$1B cumulative cash back, and a rise in retailer incremental profit from $605M in 2024 to $707M in 2025. Feedback suggests repeated inclusion on growth rankings (e.g., Inc. 5000, Deloitte Technology Fast 500) further reflects momentum and visibility.
Strategic Partnerships: Feedback suggests partnerships and integrations broaden distribution and merchant adoption, including Marqeta and rollouts with large operators such as Save Mart and major QSR franchise groups. Feedback suggests these alliances extend Upside’s reach beyond the standalone app via partner networks that help drive consumer exposure and category expansion.

MVF powers growth for our clients by connecting them to potential customers. The digital marketing landscape is complex and constantly evolving. Businesses need experts who are tracking that evolution and finding new ways to innovate and win. This is where MVF comes in. We match readers, buyers, & business leaders with the brands & companies that make the products and services they...

MVF's Top Stability & Growth Strengths
Market Expansion: The company continues to broaden its geographic footprint, operating from London and Austin and serving clients across the UK, US, Europe and beyond. Management highlights that the B2B Americas business has more than doubled and the Austin operation has continued to expand, alongside repeated recognition for international sales growth.
Investor Backing & Capital Strength: Private‑equity backing from Bridgepoint and dedicated financing facilities have been cited as supporting ongoing organic growth and acquisitions. This sponsorship signals access to capital and institutional support for scaling.
Resilient & Sustainable Growth: Evidence points to sustained expansion over time, including reported FY2023 turnover growth and division‑level gains such as 68% year‑over‑year in a B2C EMEA team. Company materials and historical rankings depict a long‑running growth trajectory complemented by ongoing investment in technology and selective M&A.

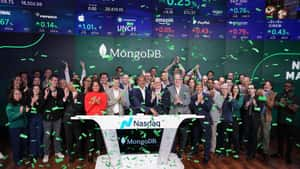
The database market is big. How big? Well, according to IDC, it’ll reach $153 billion by 2027. And MongoDB is at the forefront of that innovation with thousands of customers across the globe. We empower developers and businesses to build and deploy the applications they want, wherever they want.
MongoDB's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue expanded at a faster year-over-year pace in the latest quarter, with multi-year increases continuing from prior fiscal years and momentum building into fiscal 2027. Recent disclosures indicate broad-based gains across subscriptions and both cloud and self-managed offerings.
Healthy Cash Flow: Operating cash flow rose sharply year over year, and free cash flow expanded alongside improving operating margins. There is also a shift to GAAP profitability, signaling stronger operating leverage.
Customer Loyalty & Retention: A high net ARR expansion rate indicates existing customers are spending more over time, complementing steady additions to the total customer base. Atlas-related consumption from larger existing accounts is cited as a key driver of subscription growth.
.png)
Apex Fintech Solutions provides the tools and services that enable hundreds of clients to launch, scale, and support digital investing for tens of millions of end investors. The company provides essential infrastructure and a comprehensive ecosystem of cloud-based products to enable and streamline trading, wealth management, cost basis, tax reporting, and, through its subsidiary Apex Clearing™, custody and clearing. For...

Apex Fintech Solutions's Top Stability & Growth Strengths
Product Line Growth: Product scope has widened beyond core clearing/custody, with launches such as Apex Ascend (real-time, cloud-native infrastructure), Apex Alts, and new capabilities like AI tools, prediction markets, and direct indexing, plus acquisitions including FinTron and AdvisorArch. These additions indicate a broader platform designed to serve more wealth-tech workflows and asset types.
Strategic Partnerships: Recent announcements highlight collaborations with major platforms and institutions, including Cash App Investing selecting Apex as a strategic clearing platform, Gemini choosing Apex for U.S. stock-trading custody/clearing, and integrations/alliances with Plaid, Google Cloud, and State Street. These relationships point to expanding distribution and external validation of the offering.
Strong Market Position & Advantage: Operating scale is substantial, with company-reported figures of hundreds of billions in assets under custody, tens of millions of accounts, and hundreds of millions of annual trades, alongside support for 200+ platforms. High-profile platform selections reinforce a durable position in digital investing infrastructure.

At General Motors, our vision is to create a world with Zero Crashes, Zero Emissions, and Zero Congestion. We wholeheartedly embrace the responsibility to lead the change that will make our world better, safer, and more equitable for all. Our industry and company are undergoing a once-in-a-lifetime technological transformation, which is reshaping our approach to technology and innovation. We are expanding...
General Motors's Top Stability & Growth Strengths
Profitability: Profitability is trending upward in 2026, with management twice raising full-year adjusted EBIT guidance and North America’s EBIT margin improving to 8.6%. Strong demand, improved margins, lower EV losses, and higher operating efficiency are cited as drivers.
Strong Market Position & Advantage: Market position in the U.S. remains strong, with 2025 deliveries up 6% to about 2.9 million and market share rising to roughly 17.2%, alongside leadership in full-size pickups and full-size SUVs. Several brands posted record or decade-best results, and crossovers grew to more than 46% of sales by Q1 2026.
Healthy Cash Flow: Cash generation is viewed as robust, with executives indicating more than $10 billion of free cash flow per year on average over the last five years. Capital returns were reinforced by a higher dividend and a new $6 billion share repurchase authorization.
“In 36 months, agentic AI systems will be an operating reality across major institutions. We intend to be central to it.” — Dr. Jim Rebesco, Cofounder and CEO, Striveworks The next era of American leadership will be defined by whether our AI systems can work when and where it matters most. Since 2018, Striveworks has delivered the most trusted AI...
Striveworks's Top Stability & Growth Strengths
Market Expansion: A multi-year U.S. government enterprise agreement with a $70M ceiling and subsequent Army task orders indicate scaled access and active utilization across defense agencies. Participation in the Army’s NGC2 efforts and deployments spanning the Army, Navy, and Combatant Commands point to a widening program footprint.
Investor Backing & Capital Strength: A 2026 Series B growth investment led by Washington Harbour Partners, following a prior $33M institutional round, signals strengthened capital support. Management explicitly tied the new capital to expanding engineering, R&D, and delivery capacity.
Strong Revenue Growth: Earlier independent coverage cited very rapid ARR growth over a multi-year period and recognition among fast-growing technology companies. These signals collectively suggest meaningful historical revenue momentum even without current audited figures.
Corporate Tools is proudly, stubbornly independent. No outside investors calling the shots. It’s just us choosing customers over profits, every time. We build the behind-the-scenes tools that keep businesses running: software, LLC filings, registered agent service, website and domain registration, address services… basically all the unglamorous stuff that makes companies actually work. We’ve grown into one of the largest B2B providers in...

Corporate Tools LLC's Top Stability & Growth Strengths
Diversified Revenue Streams: The company highlights expansion beyond core registered‑agent/entity services into telecommunications, domain registration, credit card processing, and data centers. This breadth indicates multiple monetization channels rather than reliance on a single line of business.
Product Line Growth: Corporate Tools describes broadening its offering to include entity management software, nationwide filings/logistics, compliance tooling, and related infrastructure. This expansion in scope aligns with continued scaling across a larger operating footprint.
Investor Backing & Capital Strength: Corporate Tools characterizes itself as independently owned and debt‑free. That footing suggests financial flexibility without dependence on external capital markets.

Commerce (Nasdaq: CMRC) empowers businesses to innovate, grow, and thrive through an open, AI-driven commerce ecosystem. As the parent company of BigCommerce, Feedonomics, and Makeswift, we help brands unlock the full potential of their data, connect systems, and deliver seamless, personalized experiences across every channel. Visit commerce.com or follow us for more. #PoweredByCommerce

Commerce's Top Stability & Growth Strengths
Profitability: GAAP net income turned positive in Q1 and Q2 2026 and non‑GAAP operating margin improved year over year, indicating meaningful bottom‑line progress. Adjusted EBITDA also increased, supporting a trend toward sustainable earnings.
Cost & Operational Efficiency: A September 2026 operating plan targets approximately $60M–$80M in annualized cost savings and raised operating income guidance, reflecting disciplined execution. Positive operating cash flow and sequential margin gains point to improving operational leverage.
Future-Ready Strategy: Product moves highlight AI- and agentic‑commerce capabilities and payments initiatives (e.g., BigCommerce Payments by PayPal) across BigCommerce, Feedonomics, and Makeswift. This orientation suggests readiness to better monetize growing GMV and new channels.
A global leader in applied safety science, UL Solutions transforms safety, security and sustainability challenges into opportunities for customers in more than 100 countries. UL Solutions delivers testing, inspection and certification services, together with software products and advisory offerings, that support our customers’ product innovation and business growth. The UL Certification Marks serve as a recognized symbol of trust in...

UL Solutions's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has increased for multiple consecutive years, surpassing $3.0B in 2025 with continued growth into early 2026, including positive organic gains across all major segments. Filings indicate the trajectory is broad-based rather than acquisition-driven.
Profitability: Profitability is expanding faster than sales, with strong adjusted EBITDA growth and notable margin improvement in 2025. Subsequent quarterly updates show further gains, reinforcing operating leverage.
Healthy Cash Flow: Operating cash flow increased to roughly $600M in 2025, with stronger free cash flow supporting continued investment in labs and capacity expansion. This cash generation underpins ongoing growth initiatives.

From solo developers building their first app to large enterprise teams if it needs to be fast, reliable, and beautifully built, it runs on Vercel. Our platform powers millions of deployments a day. We started with a simple belief: the web should be fast for everyone, everywhere. That belief became Next.js. Then a platform. Then the infrastructure layer for the...
Vercel's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is described as rising from roughly $100M in early 2024 to about $340M by early 2026, with continued momentum into 2026. This trajectory is reinforced by reports of substantial run‑rate increases alongside expanding platform usage.
Investor Backing & Capital Strength: A $300M Series F at a $9.3B valuation—reported as oversubscribed and a marked step‑up from 2024—signals strong access to capital. Co‑lead participation by Accel and GIC underscores depth of investor demand.
Innovation-Driven Growth: AI offerings such as v0 are portrayed as rapidly scaling, with millions of users and a significant share of deployments initiated by coding agents. Platform metrics like daily deployments and AI Gateway usage indicate innovation is driving adoption and workload growth.
.png)
Arrive Logistics is a top 4 American truckload brokerage headquartered in Austin, Texas, with 10 locations across North America. Founded in 2014, Arrive delivers unparalleled service and custom strategic solutions to a diverse network of globally recognized brands and vetted carriers. Arrive has 2,000 employees, 5,500 customers, and 10,000 core carriers in its network. The Company has been recognized for...

Arrive Logistics's Top Stability & Growth Strengths
Strong Revenue Growth: Company-reported revenue around $2.7B in 2025 with a Q4 run-rate near $3B, and leadership indicating a >$4B run-rate in 2026, point to ongoing scale gains. Freight volume rising roughly 25% in 2024 and more than 20% year over year in 2025 reinforces the upward trajectory.
Investor Backing & Capital Strength: A majority equity investment by Mubadala Capital is presented as fueling the next phase of growth without adding deal-related debt. The transaction is tied to expanding services, technology, and talent, including plans to hire 1,000 people in 2026.
Strong Hiring & Retention: Headcount moved past 2,000 with 500 hires in 2024 and 650 in 2025, with roughly 1,000 additional hires planned for 2026. Company updates also cite record‑low attrition alongside productivity gains.
Build what’s next — with tech that matters PwC provides professional services across Audit and Assurance, Advisory and Tax — powered by a global network of over 370,000 people in 149 countries. You may know us for our business expertise, but technology is core to how we help clients move faster, build trust and deliver meaningful outcomes. As a technologist, you’ll work...

PwC's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Revenue has increased year over year to a new high, with all three major service lines posting gains despite a slower pace. Growth remains uneven by region, but the overall trajectory is upward over the last several fiscal years.
Future-Ready Strategy: Multi‑billion‑dollar investments in technology—especially nearly $1.5B in AI—along with acquisitions and scaling managed services indicate a deliberate pivot to future growth levers. Leadership attention to next‑generation audit and AI‑enabled capabilities underscores preparation for emerging demand.
Strong Market Position & Advantage: The organization is characterized as a leading global professional‑services network with broad scale across assurance, advisory, and tax and repeated external recognitions in select consulting categories. Reach across major multinational clients supports durable competitive positioning.

We offer a source to pay solution designed for the energy sector. It streamlines the entire process from finding suppliers to issuing payments. Our goal is to strengthen alignment between field workers and corporate offices.

RigUp's Top Stability & Growth Strengths
Strong Revenue Growth: Historical metrics indicate rapid scaling, with gross revenue rising from under $300M in 2018 to roughly $900M in 2020. Platform volume also surpassed $2B in 2019 alongside very strong year-over-year growth at that time.
Investor Backing & Capital Strength: The company secured major financings, including $300M rounds in 2019 and 2021 at valuations of about $1.9B and $2.9B, bringing total funding above $750M. These rounds signal strong investor confidence during periods when the business was scaling across customers and service categories.
Product Line Growth: Offerings expanded beyond a labor marketplace into an energy-specific source-to-pay and vendor management platform, with additions such as bid management, technology licensing, and an engineering acquisition. Recent moves like launching vendor management, licensing Shell’s U‑lateral technology, and acquiring Codeco‑Vanoco Engineering suggest ongoing product and capability expansion.
Apptronik is building robots for the real world to improve human quality of life and to help solve the ever-increasing labor shortage problem. Our team has been building some of the most advanced robots on the planet for years, dating back to the DARPA Robotics Challenge. We apply our expertise across the full robotics stack to some of the most...

Apptronik's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor participation is substantial, with nearly $1B raised across Series A tranches and backing from corporates like Google and Mercedes‑Benz to fund production and deployment. Feedback suggests this capital base is intended to accelerate scaling of Apollo and broader operations.
Strategic Partnerships: Partnerships span Mercedes‑Benz, GXO Logistics, Jabil, and Google DeepMind, moving Apollo from demos into pilots and industrial integrations. These relationships indicate advancing commercialization and access to manufacturing and AI capabilities.
Strong Hiring & Retention: Headcount expanded into the hundreds with senior hires from Waymo, Boston Dynamics, and Amazon to drive commercialization. Public statements note continued hiring to support production, facilities build‑out, and deployments.

Founded in 2015, ReUp Education is the only organization that focuses exclusively on helping colleges and universities engage and re-enroll the more than 40 million US residents who have "stopped out" and support them until graduation, through our technology-enabled service. Today we build regional marketplaces to connect the supply of educational opportunities with the demand for skilled and credentialed workforce...

ReUp Education's Top Stability & Growth Strengths
Strong Revenue Growth: Inclusion on the Inc. 5000 list in both 2025 and 2026 is cited as direct evidence of multi‑year revenue growth. Consecutive recognition implies sustained top‑line expansion over the measured period.
Market Expansion: Partner counts rose from about 140+ colleges and universities across 33 states in 2025 to 160–180+ partners across 34 states by 2026. New statewide and institutional engagements in places such as Michigan, New Jersey, Massachusetts, and additional colleges indicate a widening geographic footprint.
Strategic Partnerships: State‑level programs (for example, New Jersey’s statewide re‑enrollment marketplace and Michigan’s multi‑institution initiative) show deepening relationships beyond single campuses. Ongoing additions like Montgomery County Community College and Mineral Area College reflect continued partner acquisition.
Grocery TV is the leading in-store retail media platform. Over 120 retailers partner with Grocery TV to modernize their stores and drive incremental revenue, while upholding a high-quality shopper experience. Grocery TV handles the complexities of operating an in-store media network so retailers can focus on what they do best—serving their customers. Reaching 1 in 4 Americans across nearly 6,000...
Grocery TV's Top Stability & Growth Strengths
Strong Revenue Growth: Multi‑year revenue gains are documented through repeated Inc. 5000 recognition and company‑reported growth over recent periods, indicating sustained top‑line momentum. Public materials consistently position revenue expansion alongside broader network scale increases.
Market Expansion: The network footprint has scaled quickly in stores, screens, and shopper reach, with continued additions of retailers and locations across the U.S. Announcements highlight step‑ups from earlier milestones to a materially larger national presence.
Strong Market Position & Advantage: The platform is frequently characterized as the largest in‑store retail media network for U.S. grocery, suggesting a scale advantage across banners and geographies. Third‑party trade coverage and company materials align on leadership by store and screen footprint.

At Graphcore, we’re building the future of AI compute. We’re a team of semiconductor, software and AI experts, with deep experience in creating the complete AI compute stack - from silicon and software to infrastructure at datacenter scale. As part of the SoftBank Group, backed by significant long-term investment, we are delivering key technology into the fast-growing SoftBank AI ecosystem....

Graphcore's Top Stability & Growth Strengths
Investor Backing & Capital Strength: SoftBank ownership and subsequent capital deployments are described as materially strengthening the company’s funding base, with multiple 2025–26 share allotments and later injections supporting expansion. Evidence indicates this provides far greater financial backing than before the acquisition.
Strong Hiring & Retention: Plans to double UK headcount to around 750 and create 500 semiconductor roles in India signal substantial workforce expansion. The company also indicated immediate hiring of 100 India engineering roles, suggesting growth already underway.
Market Expansion: Announcements of a new AI Engineering Campus in Bengaluru and additional international offices point to a broader geographic footprint. These moves indicate active scaling of R&D capacity across regions.
ePayPolicy offers easier payment tools, built just for insurance. ePayPolicy's products bring insurance payments up to speed for agencies, carriers, MGAs and PFCs, with secure online payment pages, automated check processing, accounting reconciliation and more. 11,000+ insurance companies trust ePayPolicy and their expert support team to handle their payments every day.

ePayPolicy's Top Stability & Growth Strengths
Strong Revenue Growth: Inc. 5000 placements across five consecutive years, including a recent cycle with triple-digit multi‑year growth, indicate sustained revenue expansion. Earlier cycles cited even higher multi‑year growth, reinforcing a pattern of continued momentum.
Market Expansion: Customer count reportedly advanced from roughly 7,000 organizations to 10,000+ in 2025 and 12,000+ in 2026. This trajectory points to broader adoption across agencies, MGAs, carriers, and premium finance companies.
Investor Backing & Capital Strength: A new investment from LLR Partners in August 2025, alongside existing backer Serent Capital, was framed to support the next stage of growth. This institutional backing signals capacity to fund product innovation and go‑to‑market expansion.
For more than two decades, Imprivata has been redefining how life- and mission-critical industries secure and manage digital identities. We empower healthcare and enterprise organizations to enable fast, compliant, and secure access to technology—allowing clinicians and staff to stay focused on what matters most: patient care and operational excellence. Our digital identity platform is purpose-built for complex environments where every second...

Imprivata's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as sizable and growing rapidly, with independent reporting and credit analyses pointing to continued double‑digit expansion. ARR and ACV are characterized as increasing consistently since 2022.
Customer Loyalty & Retention: Retention is depicted as very high, with consistent expansion within existing accounts that supports sustained recurring revenue growth. Commentary highlights strong share‑of‑wallet gains and durable renewals across healthcare customers.
Product Line Growth: The portfolio has broadened through repeated acquisitions (e.g., SecureLink, Verosint) and new capabilities such as passwordless authentication and agentic identity management. These moves signal active investment to expand addressable use cases and deepen the platform.
.png)
Navan (Nasdaq: NAVN) is the leading all-in-one business travel, payments, and expense management platform that makes travel easy for frequent travelers. From finding flights and hotels to automating expense reconciliation, with 24/7 support along the way, Navan delivers an intuitive experience travelers love and finance teams rely on. See how Navan customers benefit and learn more at navan.com.

Navan's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is scaling at strong double-digit rates, reaching $702M in FY2026 and continuing to rise in subsequent quarters, with full‑year FY2027 guidance lifted into the low‑$900M range. Multiple updates indicate momentum in both reported results and outlook.
Healthy Cash Flow: Operating cash flow turned positive in FY2026 and free cash flow was also positive, alongside progress in non‑GAAP profitability in later quarters. These milestones suggest improving financial efficiency as scale increases.
Diversified Customer Base: The company reports 12,500+ active customers and continued wins with large enterprises across technology, manufacturing, and healthcare. This breadth points to demand resilience across multiple industries.



